Shops, flats under one roof.
Schemes where high-street lenders draw the line between residential and commercial. We underwrite the whole asset on its merits, not just the easy half.
- Loan size
- £250k – £1.5m
- Term
- 3 – 12 months
- LTV
- up to 70%
- Rates from
- 0.79% / month
- Exit fees
- None
- Geography
- England
- Security
- 1st charge + Ltd Co. debenture & PG
- Borrower
- Ltd Co., LLP or sole trader
What we lend on.
We’re specific about what we do. If your deal isn’t on the list, ask anyway. We’ll tell you straight.
Shop & uppers
Ground-floor retail with self-contained flats above.
Pub & uppers
Trading or vacant pubs with residential potential.
Live-work
Workshops, studios and live-work units.
Part-let buildings
A mix of leases, tenancies and licences.
Re-positioning
Converting the commercial element to residential.
Air rights
Adding storeys above existing commercial space.
Where we generally don’t lend
- Schemes where a loss-making commercial element dominates the value
- Residential elements on leases of under 50 years
- Ground-up development with no existing structure
Recent deals. Real outcomes.
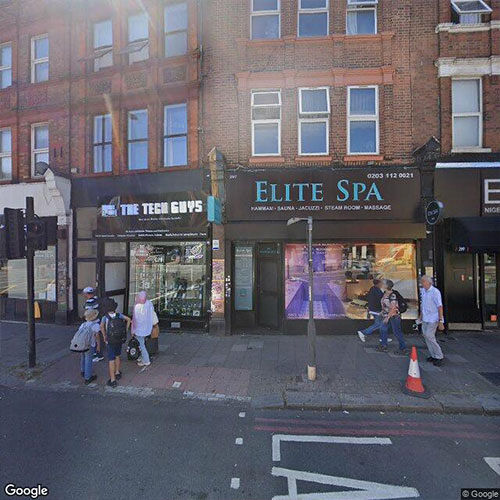
All projects- Camden, NW1
Camden bridge loan
A first-charge bridge on a Camden property.
- Loan
- £315,000
- LTV
- 70%
- Security
- First charge
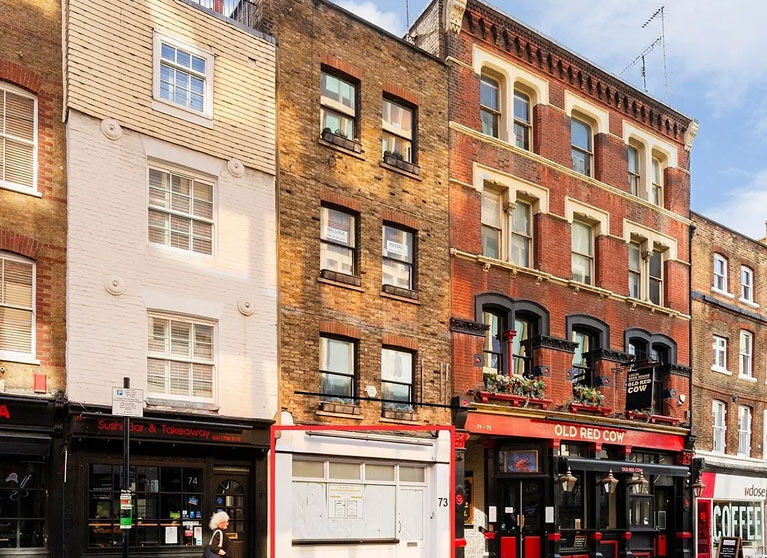 Shoreditch, EC2
Shoreditch bridge and development loan
A three-tranche, asset-backed bridge and development loan, finalised in partnership with the borrower.
- Loan
- £600,000
- LTV
- 46%
- Security
- First charge and debenture
Three steps. One person.
- 4 hrsto an indication
Talk to our team
Speak with one of our dedicated experts, who will assess your needs and guide you through the process.
- 1named contact, start to finish
Complete a simple application
Fill out our streamlined form with the essential details, for a fast and tailored review of your deal.
- 2–3 wkstypical drawdown
Receive a swift decision
Terms confirmed in writing, then funds released on completion, with the same person on your file throughout.
Mixed use questions.
How do you value a mixed-use building?
We instruct a valuer to report on the whole asset, apportioning between the elements where useful. The lower of bricks-and-mortar or investment value drives the advance.
What if the commercial element is vacant?
That’s fine. We’ll take a view on the residential value with an allowance for the vacant space. Often the cleanest plan is to convert it.
Will a 1st charge be enough?
For a sole trader or LLP, usually. Every loan to a limited company also needs a debenture and a personal guarantee.
Other sectors
Got a mixed use deal? Let’s talk.
Send us the headline numbers and we’ll come back within four working hours with indicative terms, or tell you straight if it’s not for us.